THE HOME INVENTORY TOOLKIT™
PROOF FOR EVERYTHING THAT MATTERS
You get paid for what you can prove. Not what you had. Not what you paid.
What you can prove!
I disputed $7,411.75 of my own insurance claim and they paid every penny of it, no questions asked. This is how.
OUR CHRISTMAS STORY:
Nothing Was Calm. Nothing Was Bright.
Twas the night before Christmas and all through the house not a creature was stirring, not even a mouse, when the fire alarms shrieked and we ran for the hall, where a pipe two floors over had let go of it all.
It came down through the ceiling and took the whole place, and we spent the week of Christmas in a hotel, totally displaced.
Then the offer came in, and I read it, and stared: our king was a twin in the numbers they shared, one twenty-nine ninety to cover two grand.
So I built them a file, and I built it by hand: their own comp beside my own photo, and under, the difference they owed. Not a shout. Not a thunder. Seven thousand four hundred eleven I claimed. They paid every penny. They never complained.
And now every big thing we own has a file. So the water can come. We've been ready a while.
WE HAD DONE EVERYTHING RIGHT BUT IT STILL IT HAPPENED TO US!
The week before this big freeze our apartment complex threatened all of us to ensure we winterized our apartments. I knew there was a vacant unit two floors above us so I contacted management to ensure THEY winterized the empty unit.
Needless to say, they did not!
I would've never imagined have to toss Christmas presents across to load them in a wagon to rush them across ice to chunk them in a car to save them. Much less having to essentially move out in just a few hours. It was INSANE!
And then when we thought our insurance would do us right after never missing a payment in years... we were more than wrong! But to be honest if I wouldn't have read their report line by line, I would've never known.
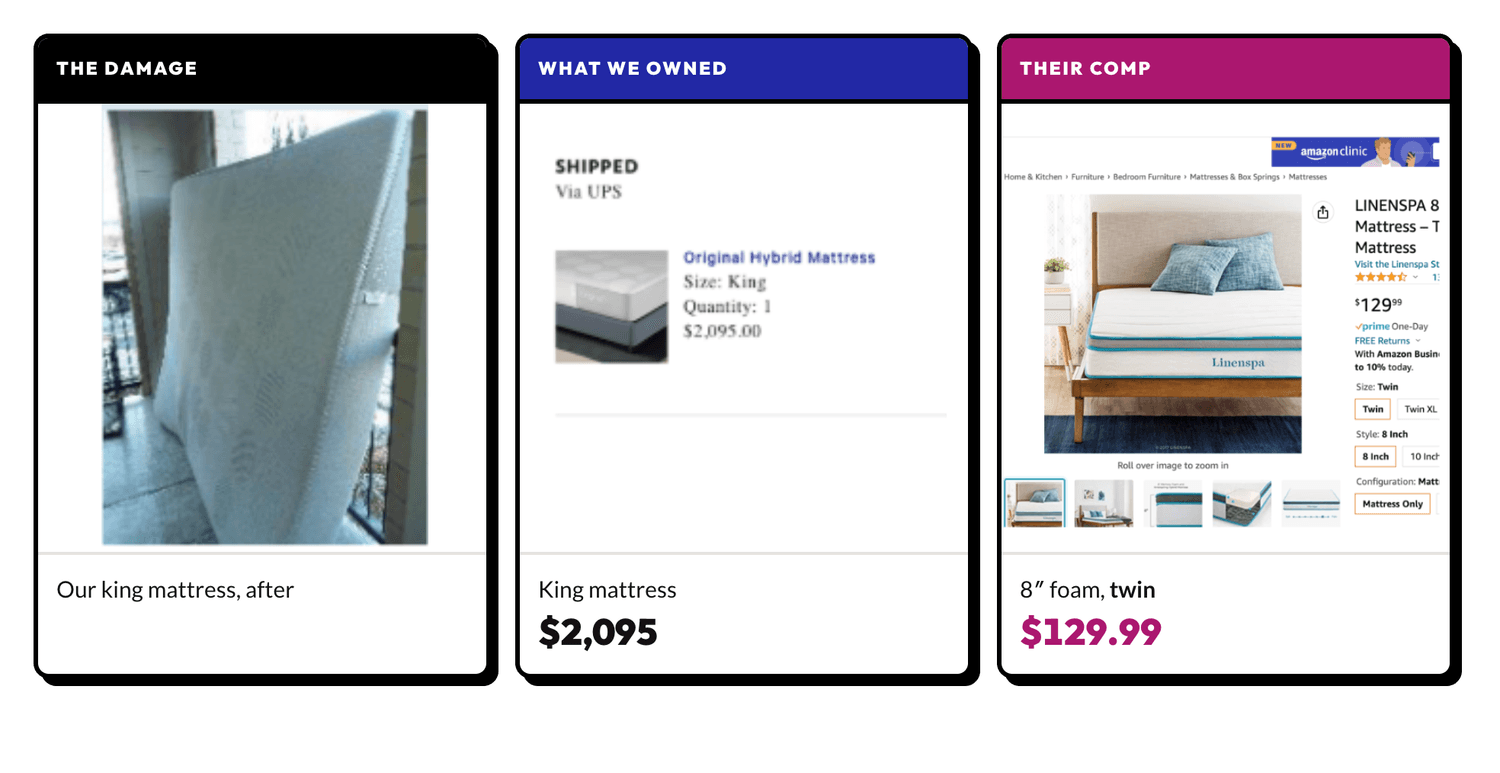
The insurance company priced our king mattress as a twin. An eight inch foam mattress, $129.99, against the $2,095 king we had been sleeping on.
Then I kept reading.
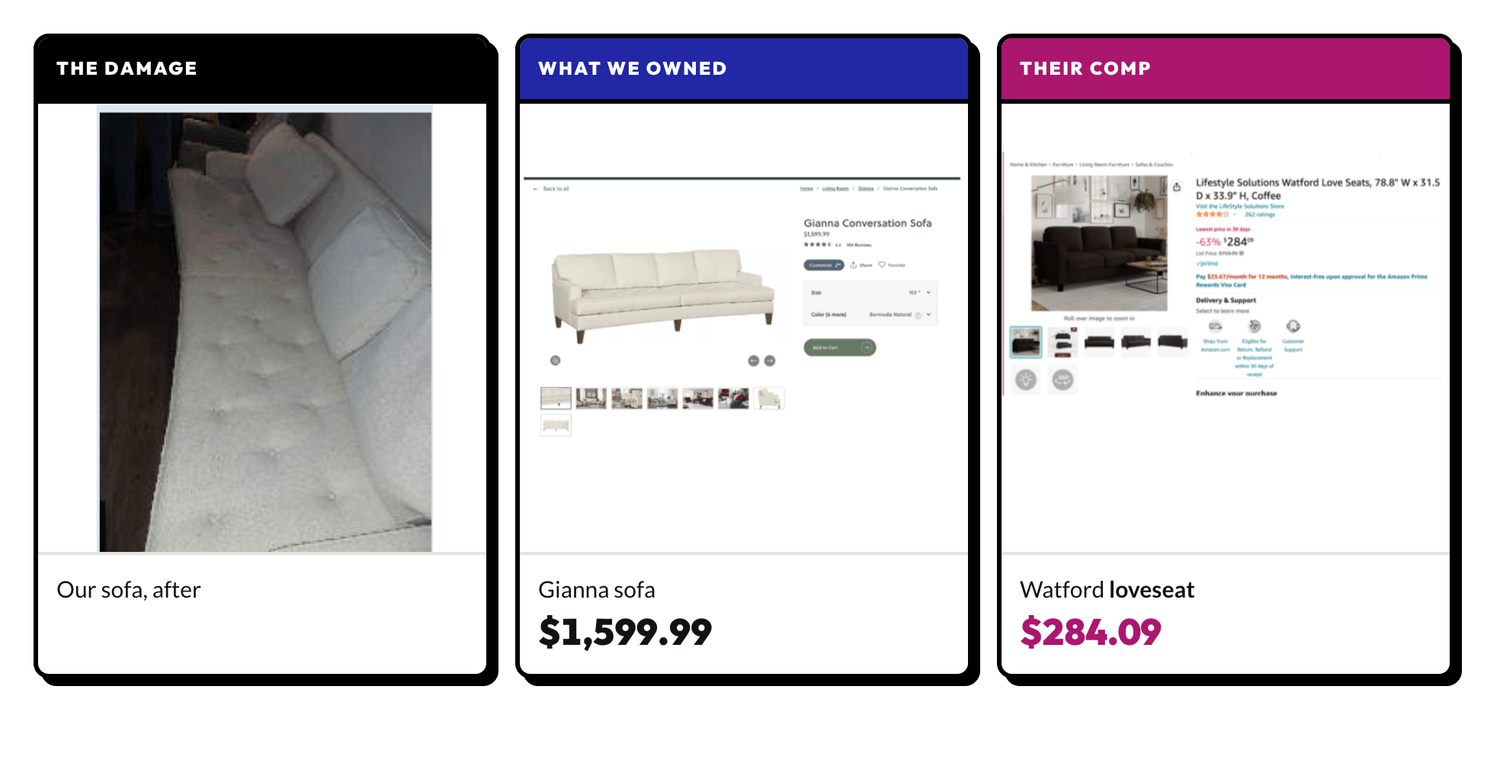
Our sofa was priced as a loveseat. $284.09 against $1,599.99.
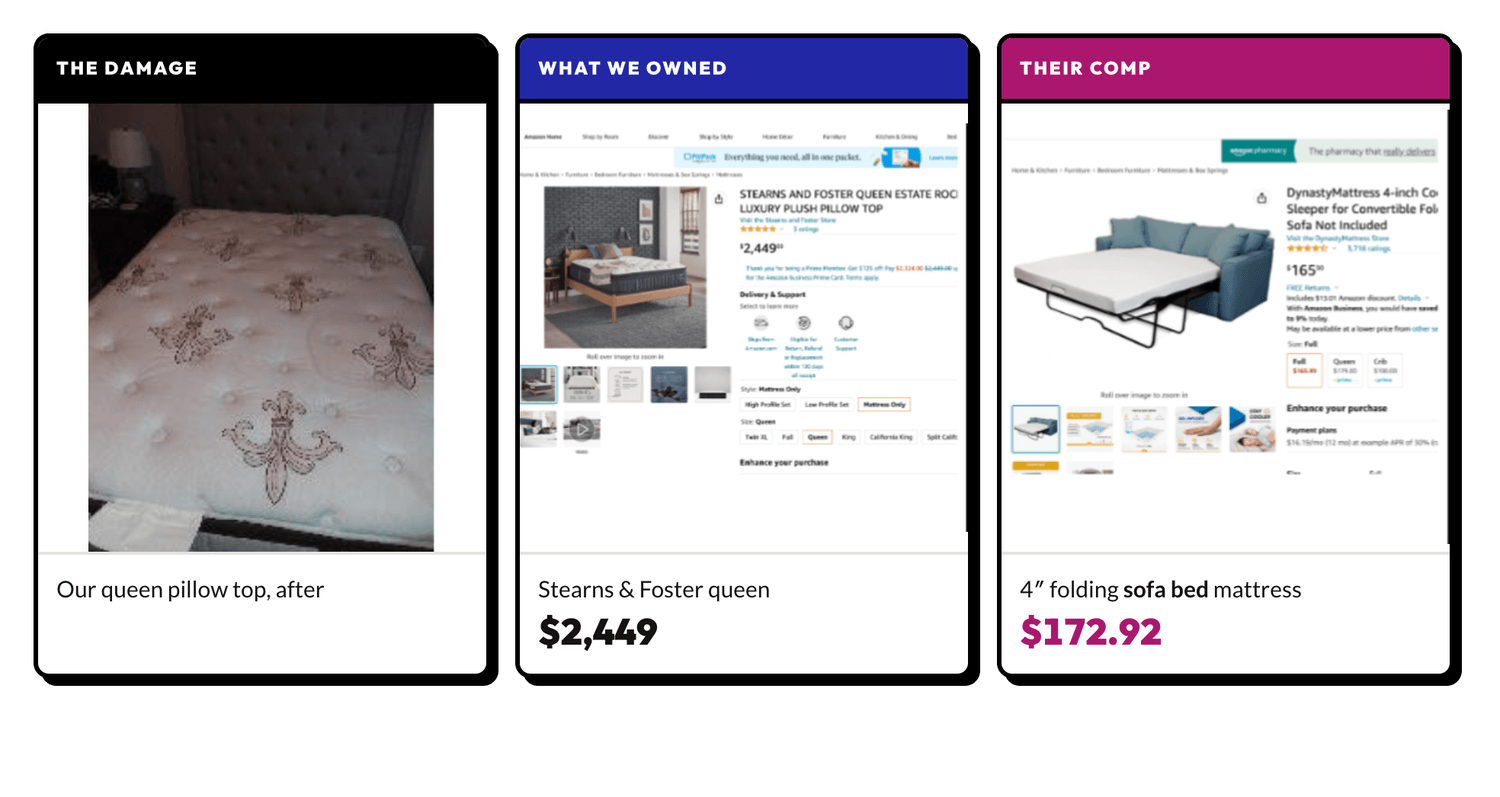
Our Stearns & Foster queen pillow top was priced as a four inch folding sofa bed mattress. $172.92 against $2,449.
Our 55 inch Samsung was priced as “TV, LCD, 29 inch or less.”
And both bed foundations, one of our bookshelves and one of our desks weren't on their list at all. Photographed, then simply not counted.
IT WASN'T THAT I ARGUED BETTER.
I CAME WITH RECEIPTS.
You know your bed is a king. Of course you do, you sleep in it.
But the brand? The model? Do you have a photo of that sofa sitting whole in your living room? Is the receipt somewhere you could actually find it in the next ten minutes, or is it buried in an email from 2020?
That's the gap. Not the size. The size is the one thing I'd have gotten right from memory, and it still wasn't enough on its own.
FOUR THINGS MAKE AN ITEM IMPOSSIBLE TO ARGUE WITH
What it actually was. Brand, model, size, condition.
What it costs to replace today, with a link and the date you pulled it.
A photo of it, whole, in your house.
The receipt, wherever you happen to have one.
Then, on the day, a fifth: a photo of the damage.
In our claim they kept swapping in something smaller. In yours it could be the brand they downgrade, the condition they assume, or an item they leave off the list entirely. You don't get to know which. So you don't prepare for one, you keep all of it.
I put all five into one document. Three columns, one row per item. What it costs today. My photo. Their comp, screenshotted, with the price they used. Underneath: replacement cost, their number, difference owed.
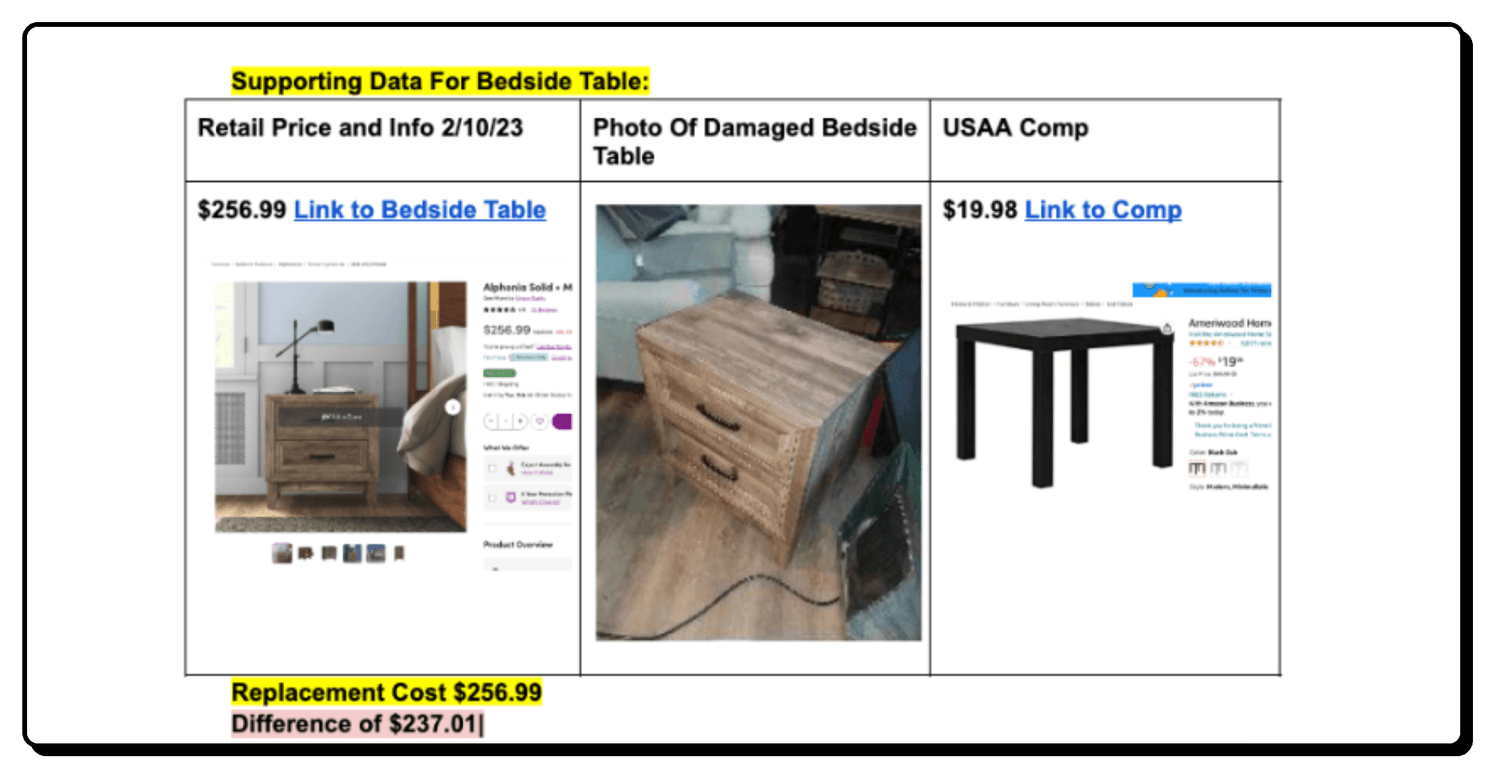
There's nothing in that to argue with. It's their own comp sitting next to a photograph and a price tag.
That's the part I want you to hear. The money wasn't in fighting. It was in the file.
And it took me about 100 hours to build.
A hundred hours of digging through years of email for receipts, hunting model numbers for furniture I could no longer look at, and standing in a hotel room trying to remember what was in a house I couldn't walk back into.
On the worst day of your life, you find out you're the only one on your side, and all you have is what you wrote down before it happened.
I hadn't written down anything. So I built it backwards, under a deadline, in the worst month we've ever had.
Every hour of that was work I could have done in advance in about a minute an item.
THIS WASN'T A ONE TIME THING.
IT NEVER IS.
OUR FORECLOSURE HOUSE
Thanksgiving weekend we discovered a pipe under the house had a spraying leak. I had to low crawl under 2000 sq feet to repair the leak. I learned more in one weekend than I ever had in my life. Despite fixing the leak the water had created mold under our entire house. When we went to sell we had to pay tens of thousands of dollars to remediate the issue for it to pass inspection.
OUR DREAM HOUSE
Runoff from the properties above us collected in our backyard the
whole five years we lived there.
THE APARTMENT
Christmas Eve. The one you just read about.
THE RENTAL HOUSE
The main line backed up, a toilet exploded, and six inches of water went through the basement. That one we were ready for. After the apartment, everything we stored went into plastic totes and every piece of furniture sat up on legs. Nothing touching the floor. We barely lost a thing.
THE HOUSE WE ARE IN NOW
New ceilings and walls were done and the floors were going in when they found water underneath. Undersized gutters, no drainage where it mattered, and a patio funneling water at the basement. We've put $30,000 into it in our first year. It could've been a total of $55,000 but we were lucky.
We decided to scope out main sewer line before we did any more work in the basement and found it packed with roots. That is the exact failure that flooded the rental basement, and it was going to cost us $25,000. Our HVAC guy is the one who mentioned the city had a program for it. They're replacing the whole line right now and it isn't costing us a thing, because we went looking before it broke instead of after.
SO HERE'S WHAT WE'RE ACTUALLY DOING IN
THIS HOUSE
Decluttering it, so there's less to lose and we know what's here.
Storing it properly, because nothing sits on a basement floor in this family anymore.
Logging it, so every big thing is documented before anything happens to it.
Fixing the systems, so the water has somewhere to go that isn't our house.
NOBODY BUT YOU...
Nobody is coming to fight for your stuff. Not your agent, not your adjuster. Just you, with whatever you can prove.
And you'll never sit down on a normal Tuesday and prepare for this. Nobody does. I didn't, the first time.
You think about it at 2am with the alarms going off. Or when you come home to a door standing open. Or when a lawyer asks who owned what.
THEFT
The police report asks what was taken. Insurance asks what it was worth. Both want it in writing, and they want it now.
DIVORCE
Who owned what, and what it was worth, stops being a conversation and becomes a legal question
MOVERS
They lose things and they break things, and their claim form wants proof of what it was and what condition it was in.
FIRE, WATER, WINDS
List everything you owned, from memory, on your worst week.
You don't get to pick which one shows up. You only get to decide whether you have proof when it does.
There's nothing in that to argue with. It's their own comp sitting next to a photograph and a price tag.
YOU'RE ABOUT TO HOLD EVERY
SINGLE THING YOU OWN.
You just bought a tool that walks you through your house one spot at a time. Over the next few weeks you're going to pick up, look at and make a decision about nearly everything in it.
That's the only time this is easy. The thing is in your hand. You can read the brand off the back of it. You still remember what you paid.
Thirty minutes now, while you're already standing there. Or a hundred hours later, when it's the last thing on earth you want to be doing.
Losing it is the part you can't control. Getting paid for it is the part you absolutely can.
You don't get to pick which one shows up. You only get to decide whether you have proof when it does.
THE HOME INVENTORY
TOOLKIT™
Proof for everything that matters most!
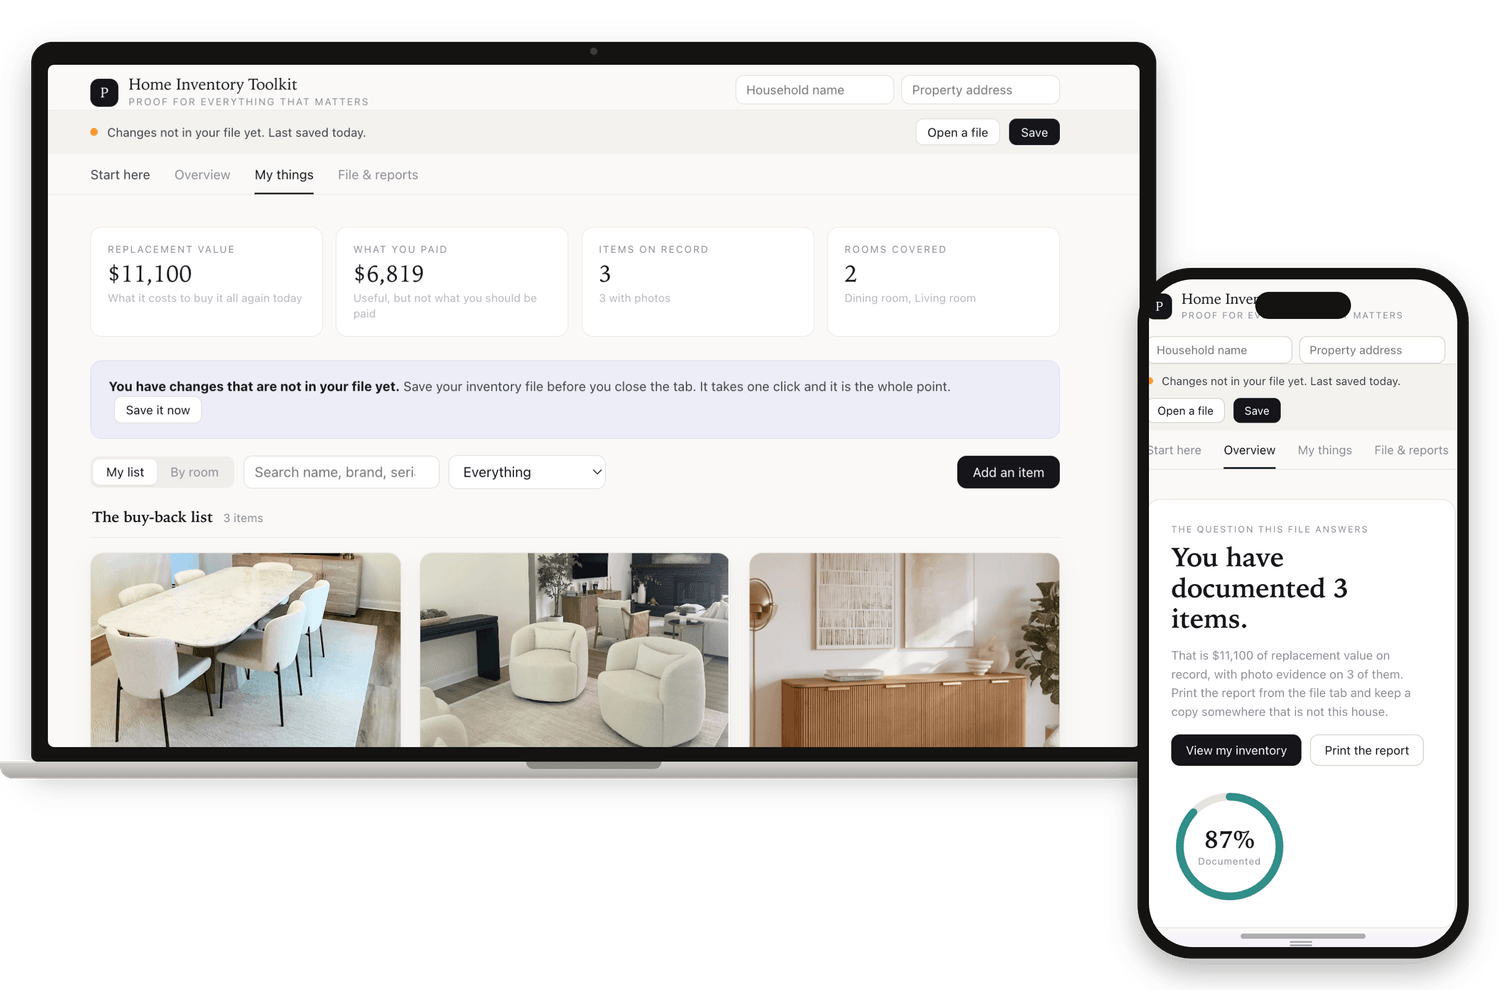
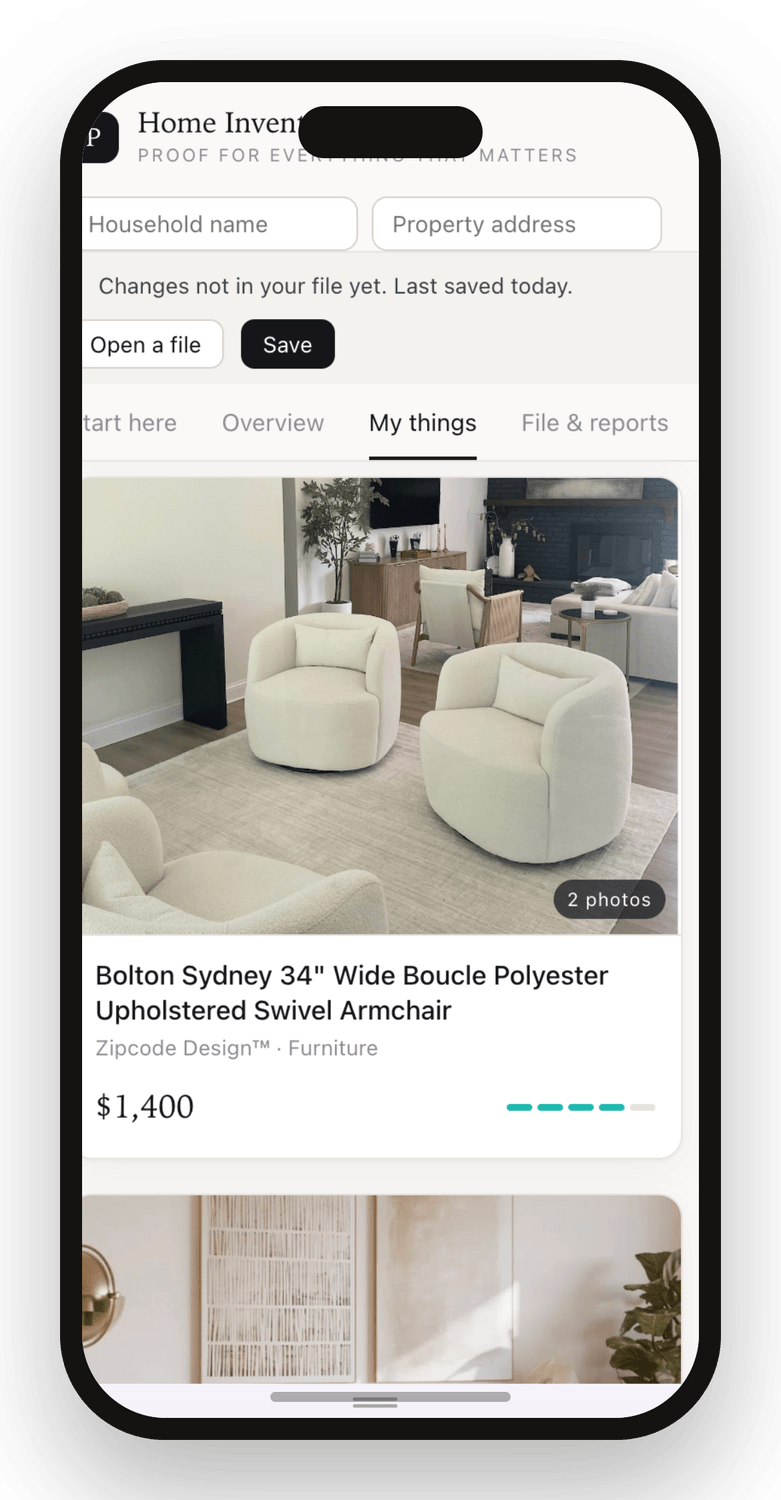
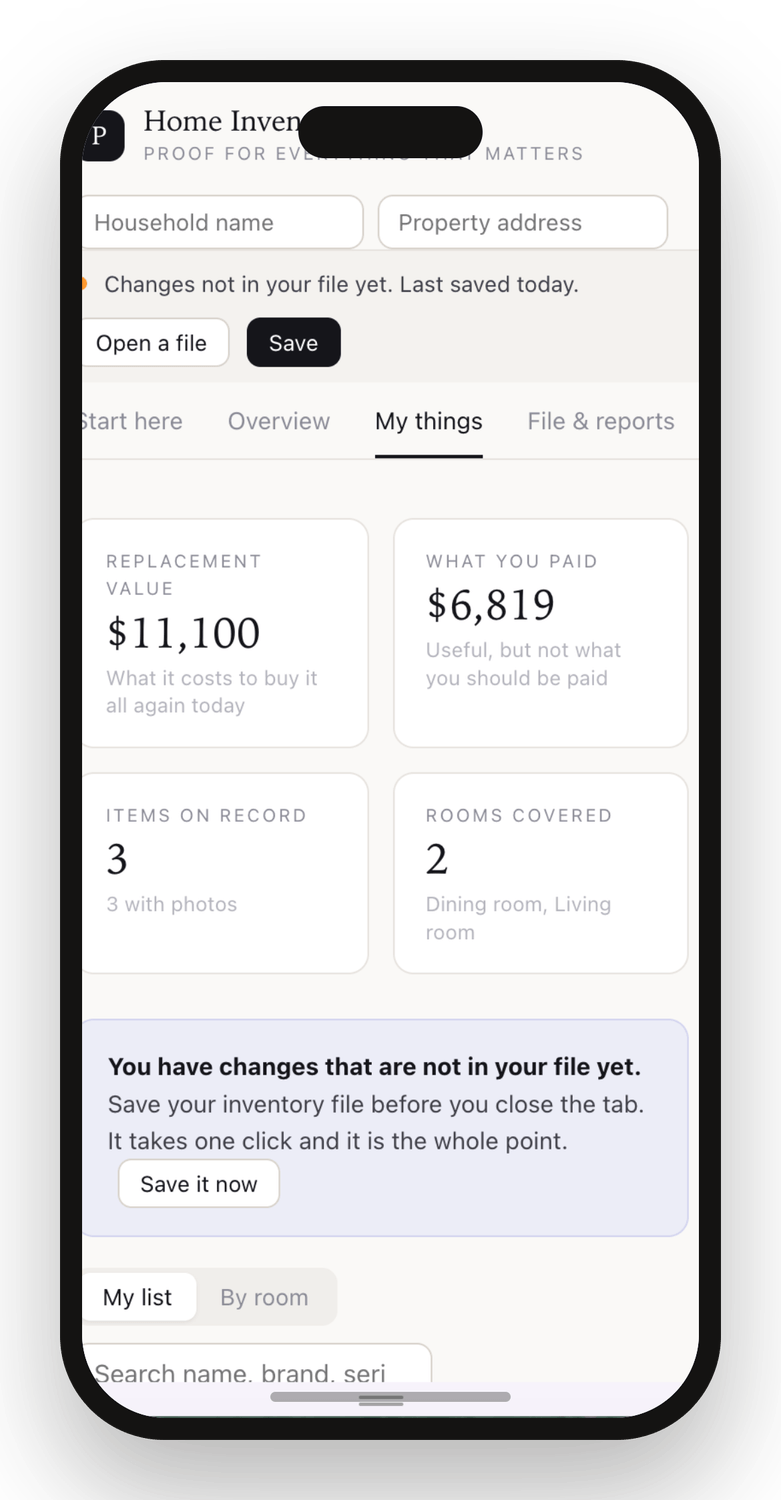
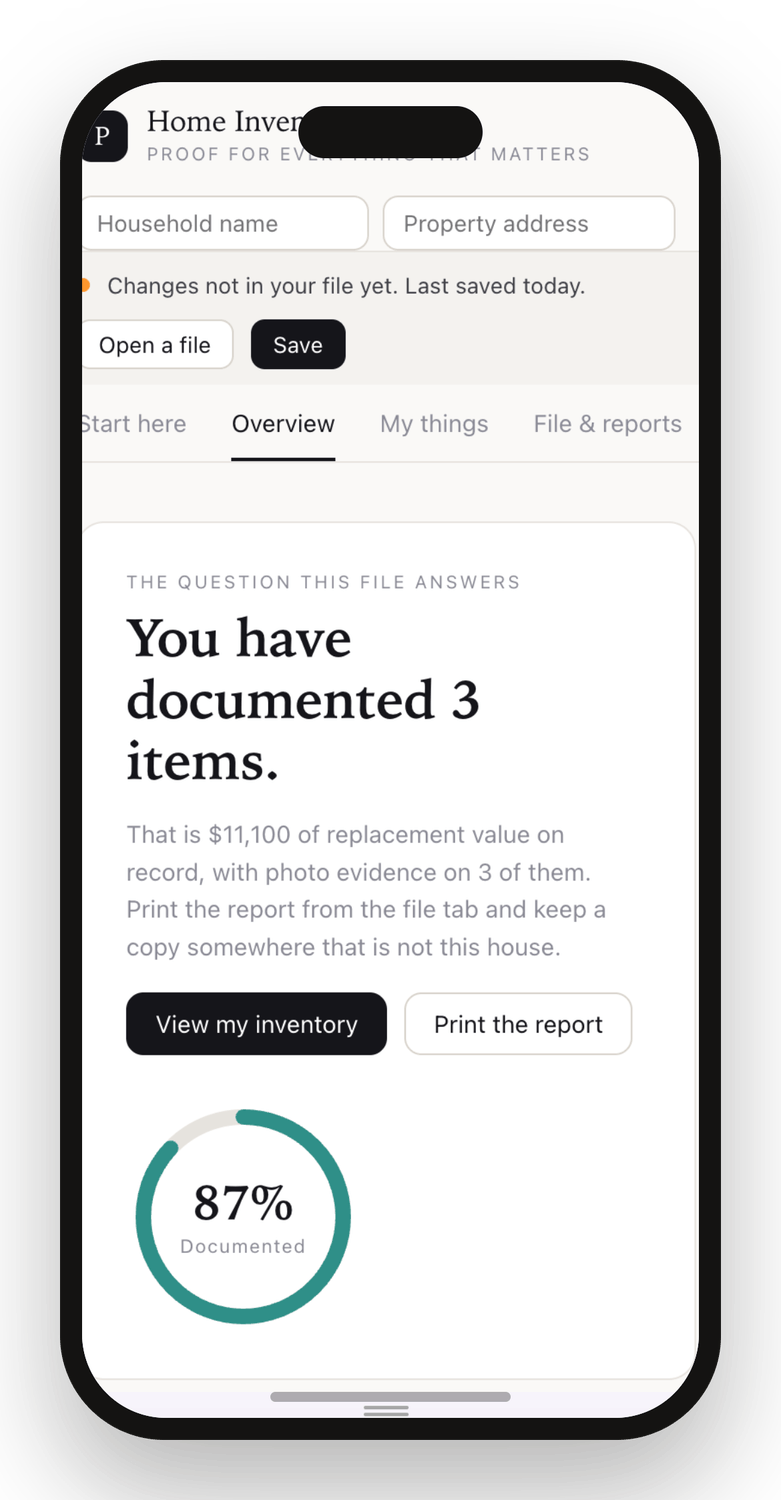
Opens on your phone, goes on your home screen in two taps. You walk your house with it.
THE BUY-BACK WALK
Session one. Photograph the things you'd have to replace in the first week. No ranking, no valuing, no deciding what counts. Beds and mattresses, sofa, dining table, fridge, washer, dryer, TV, laptop, the desk you work at, rugs, cookware. Thirty minutes, and the expensive half of your claim is documented.
THE IRREPLACEABLES WALK
Session two. Different question, different feeling. Jewelry and watches, heirlooms, anything inherited, firearms, silver, art, collections. You wouldn't need these in week one, and this is exactly where the biggest coverage gaps hide.
THE WHOLE FILE ON EVERY ITEM, IN ONE SCREEN
Brand, model, size, condition, serial number, replacement cost today, what you paid, where you bought it, photos, and the receipt or appraisal attached to the item it belongs to. Not a wizard. One page, filled in while the thing is in front of you, in under a minute.
A PROOF SCORE ON EVERY SINGLE ITEM
Scored out of five on how defensible it actually is, and it says plainly when it still needs more proof. You find out your sofa is thin on evidence while you're standing in front of it, not while you're reading an offer. Nobody else scores item by item.
ROOMS THAT BUILD THEMSELVES
Room is a field on the item, so you never open an empty room and wonder what goes in it. You walk, you log, the rooms fill in behind you.
YOUR FILES
Everything including photos in one file you keep, plus a CSV of every item and field. Put it in Dropbox, iCloud or Drive and it survives a cleared browser, a dead laptop and a house you can't get back into.
No subscription. No account. Nothing is uploaded to me, and your house is
not sitting in anybody's database.
THE HOME INVENTORY
TOOLKIT™
Proof for everything that matters most!
Opens on your phone, goes on your home screen in two taps. You walk your house with it.
BONUS 1: THE DEVIATION REPORT
THE EXACT METHOD I USED TO DISPUTE MY CLAIM
Ten pages. What a deviation is and why offers come in low. The three column format that won mine, with two worked examples built from my real claim documents, the actual screenshots and the actual numbers. Exactly what to write, who to send it to, and how to say what you're asking for.
Plus a section on how to turn your Toolkit inventory into a Deviation Report, step by step, so you're not inventing a process on the worst week of your life.
I am the only person selling anything in this category who has actually done this and won.
BONUS 2: THE ADJUSTER REPORT
GENERATED FROM YOUR INVENTORY
Room by room, with totals and a photo appendix, serial numbers optional. This is the document an adjuster asks for, and it builds itself from what you've logged. Print it or save it as a PDF the moment you need it.
BONUS 3: ITEM PAGES
GENERATED FROM YOUR INVENTORY
A PDF with one page per item. Photo, details, serial, condition and what it costs to replace. This is the one you email the day something happens, before you've had to remember a single thing. It is most of the document that got me $7,411.75, built before anything happened instead of after.
No subscription. No account. Nothing is uploaded to me, and your house is
not sitting in anybody's database.
Hiring someone to do this for you starts at around $500, priced by the size
of your house and how much is in it.
$37
YOURS TODAY-ON THIS PAGE ONLY
The Home Inventory Toolkit
$97
Bonus 1 · The Deviation Report
$97
Bonus 2 · The Adjuster Report
$97
Bonus 3 · Item Pages
$97
YOURS TODAY
$288 $37